

Ava Finance
by Ava Finance, Inc.
4.7
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.7
- Price
- Free
- Download
- 500.00K
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
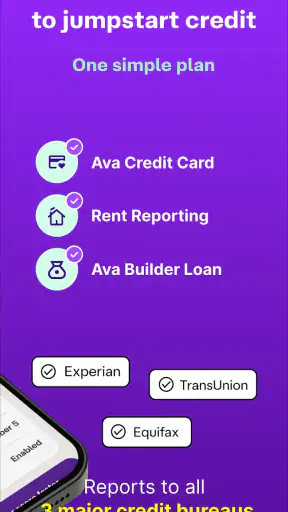
 Analysis by Getfullapps
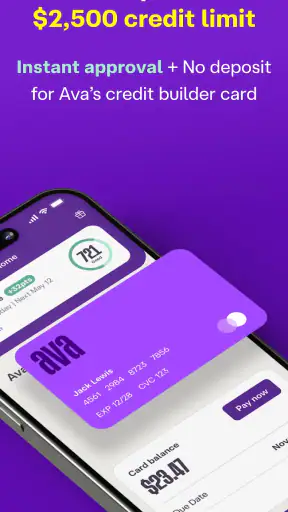
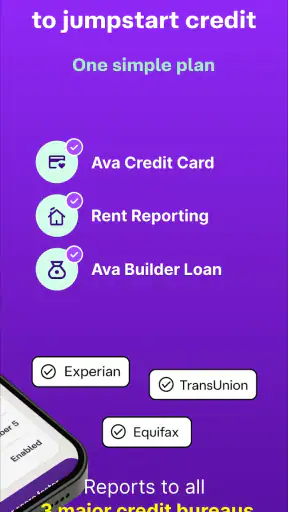
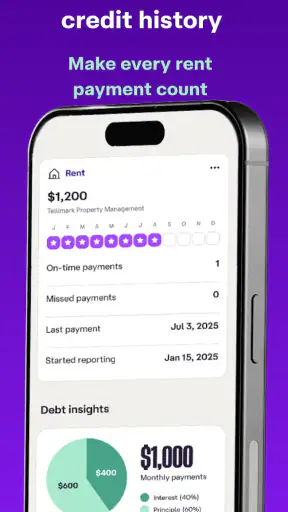
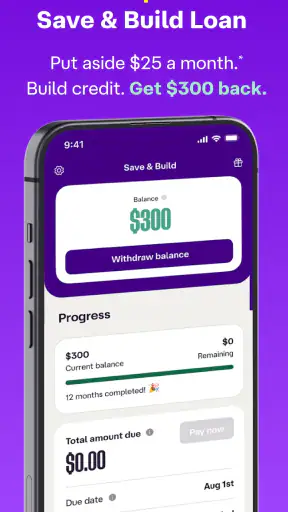
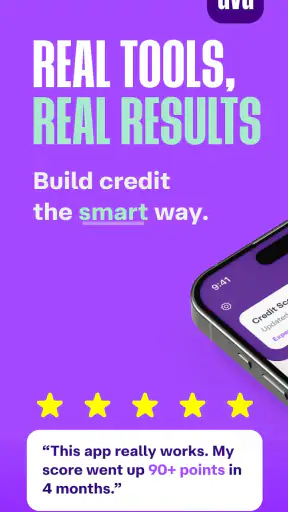
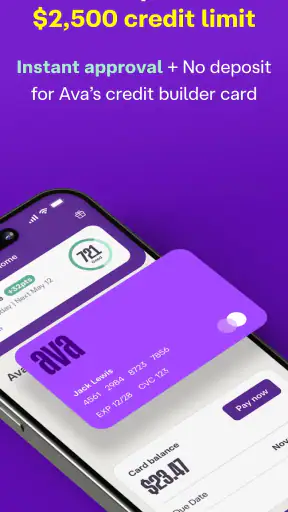
Building credit can feel strangely difficult when the thing you need most is a track record you do not have yet. That is the problem Ava Finance tries to address: it is a free finance app from Ava Finance, Inc. focused on helping people work toward stronger credit through a guided mobile experience. I found it most interesting as a practical starting point for someone who wants a clearer routine than simply opening a card and hoping responsible use eventually makes a difference.
My overall view is positive, but not blindly enthusiastic. Ava is easier to approach than many traditional credit products, and its focus is refreshingly narrow. It is not trying to be a full banking replacement, an investing dashboard, or a general-purpose budgeting suite. That focus can make it useful for a first step. At the same time, anyone expecting instant credit improvement, broad financial planning tools, or the flexibility of a conventional credit card may find the experience too limited.
How I judged Ava before recommending it
Before recommending Ava, I look at whether its focused approach fits the person’s actual goal, rather than treating a strong reputation as a guarantee of results. I also weigh how comfortably a credit-building routine can sit alongside ordinary budgeting and bill management. That distinction sets up the next question: what makes a focused app worth returning to after the initial curiosity wears off?
The first question is whether the goal is credit building
I would begin with one simple question: what do you actually want this app to do? If the answer is “help me establish or strengthen my credit habits,” Ava is relevant. If the answer is “show every account, manage investments, compare loans, and replace my bank,” it is probably not the right category of tool.
That distinction matters because credit-building products work best when they are treated as part of a routine rather than as a quick financial fix. I would look at whether the app makes the next action understandable, whether I can keep up with its requirements, and whether using it fits my existing money habits. A polished interface is helpful, but it cannot compensate for missed payments, poor planning, or borrowing more than I can comfortably manage.
I also pay attention to the difference between access and results. An app can make credit-building feel more approachable, but it cannot guarantee a particular score or outcome for every person. Credit histories differ, reporting practices matter, and time is part of the process. I appreciate Ava more when I see it as a structure for responsible behavior, not as a shortcut around the normal realities of credit.
Who is most likely to benefit
I would put Ava near the top of the list for someone who is new to credit, rebuilding after a difficult period, or simply uncomfortable with traditional card applications. It may also suit a person who prefers handling financial tasks on a phone and wants a dedicated place for a credit-focused routine instead of juggling several unrelated services.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
It is especially appealing when the main obstacle is uncertainty. Many beginners do not know which actions matter, when to check their progress, or how to avoid turning a credit product into expensive debt. A focused app can reduce that mental load. I would still expect the user to read each screen carefully and understand any obligations before proceeding, but the narrow purpose makes the learning curve less intimidating than a large financial platform can be.
On the other hand, I would hesitate to recommend it as a sole solution for someone with complicated finances. If you need detailed cash-flow forecasting, business accounting, investment analysis, or extensive account aggregation, a dedicated budgeting or banking service may be a better foundation. Ava can sit alongside those tools, but I would not confuse it with them.
What the app’s reputation tells me—and what it does not
The app has reached over 500 thousand installs and holds a 4.7 average from around 17 thousand ratings, which suggests that many people find the experience useful enough to keep using and reviewing. Those numbers give me confidence that Ava is not an obscure experiment with no visible user base. They do not, however, tell me whether it will fit a particular financial situation. A high average can coexist with frustrations from users whose expectations did not match the product’s specific purpose.
I also noticed that the app is marked for Everyone, which makes its presentation approachable rather than aimed at a specialist audience. That does not mean every financial decision inside it is automatically simple. Credit is still a serious subject, and a beginner-friendly design should be treated as an invitation to learn, not permission to skim terms.
Where Ava feels strongest in everyday use
The biggest strength is focus. When I open a general finance app, I can easily drift into checking balances, browsing spending charts, or comparing unrelated products. A credit-centered app gives the session a clearer purpose. I can think about the actions that support my credit goal instead of getting distracted by a crowded financial dashboard.
That focus also helps with habit formation. A useful workflow is to choose a regular day each week to review Ava, check what needs attention, and then close the app once the task is complete. I would not keep refreshing it throughout the day. Credit-building is usually a consistency exercise, so a short scheduled review is more sensible than constant monitoring.
A second strength is psychological: the app can make a traditionally intimidating subject feel more manageable. Someone who has avoided credit because the language seems designed for experts may find a dedicated mobile tool less overwhelming. In my experience, reducing friction at the beginning is valuable because a person is more likely to follow through when the next step is visible.
A third, less obvious advantage is that it can serve as a boundary around credit activity. I like the idea of separating credit-building tasks from everyday spending decisions. That separation encourages me to ask whether an action supports my long-term goal rather than whether it is merely convenient today. It is a small change in mindset, but it can prevent a credit product from becoming an excuse for casual borrowing.
A realistic routine for a new user
Imagine someone who has recently moved, has little established credit, and wants to prepare for future applications without taking on unnecessary debt. They install Ava, review the setup carefully, and choose a weekly check-in. On that day, they confirm that their account is in good order, read any guidance rather than dismissing it, and record questions they still have. They also keep a separate note of their wider budget so the credit routine never becomes detached from rent, food, transport, or emergency savings.
That last step is important. I would not use Ava in isolation. I would pair it with my bank’s alerts or a simple spending plan, because credit management and cash management are connected but not identical. Ava can support the credit side of the routine; it should not become the place where I assume every financial problem will be solved.
For a person in this situation, the app’s value is not a dramatic moment after installation. The value is in making responsible follow-up easier to remember. If the user cannot comfortably keep up with the app’s requirements, the correct response is to pause and reconsider rather than force the arrangement.
Where traditional alternatives may fit better
The usual alternative is a conventional secured or starter credit card. That route may be preferable for someone who wants a broadly accepted payment method, a familiar card workflow, or a direct relationship with a traditional financial institution. It can also make more sense for a user who already understands utilization, payment timing, and account management and does not need a dedicated learning layer.
A bank’s own credit tools may be better when convenience is the priority. Keeping checking, payments, alerts, and credit information under one provider can reduce the number of places I need to visit. The trade-off is that a bank’s interface may be built for existing customers rather than for someone who needs a gentle introduction to credit-building.
Credit-monitoring services are another category, but they solve a different problem. They are useful when the main need is visibility into credit information, alerts, or changes. Ava is more relevant when the user wants an action-oriented credit-building path. I would not choose one expecting it to replace the other automatically.
Budgeting apps may be the better first purchase—even when free—if overspending is the real issue. Improving credit while regularly missing essential bills is the wrong order of operations. In that case, a budget that exposes recurring expenses and creates a reliable payment buffer may deliver more immediate value than a specialized credit app.
Limitations I would consider before installing
The first limitation is scope. Ava is not the app I would open for a complete view of my financial life. If I want detailed categories, long-term savings targets, investment tracking, or a household budget shared across several people, I would look elsewhere or use another tool beside it.
The second is that a focused credit product can create false confidence if the user treats completion of in-app steps as the same thing as financial progress. I would still read the terms, understand the payment responsibilities, and check my broader budget. The app may simplify the process, but it does not remove the consequences of careless decisions.
There is also a potential mismatch between patience and expectation. Someone looking for a quick score increase may become disappointed because credit development is not an instant transaction. I would only recommend Ava to a person willing to follow a routine over time and judge success by consistent behavior, not by checking for an immediate dramatic change.
Finally, switching away later can involve more than deleting an icon. Any credit product should be reviewed for outstanding responsibilities, scheduled payments, and the effect of ending an account or routine. I would never uninstall first and investigate afterward. Before moving to a bank card, a secured card, or another credit-building service, I would make sure the current arrangement is settled and that I understand what happens to the history and obligations connected with it.
Practical tips that make the experience safer
Use a calendar reminder instead of relying on memory. A recurring weekly check-in is more dependable than opening the app only when you feel worried about your credit.
Keep a small payment buffer. Before committing to any credit-related routine, I would leave room in my budget for essential bills and unexpected expenses.
Separate education from action. Read Ava’s explanations first, then decide what you can realistically maintain. Never treat an encouraging prompt as a reason to borrow beyond your plan.
Pair it with independent records. I would keep bank alerts and a basic personal note of dates and obligations. A second record helps catch missed tasks and prevents total dependence on one app.
Review the purpose every few months. If my needs change from building credit to managing debt, budgeting, or preparing for a major application, I would reassess whether Ava still deserves a central place in my routine.
Device and access details worth knowing
Ava is free to download, which lowers the barrier for someone who wants to explore a dedicated credit-building app without committing money at the outset. Its current release is version 5.1.6626, and it supports Android 9 or later. I would check my phone’s operating system before installing, particularly if I use an older device.
The app was released on May 10, 2021, and the current version shows that it has continued receiving updates since its original launch. I see that as a practical sign for users who care about an actively maintained mobile experience, although I would still keep the app updated and review each screen after an update rather than assuming every workflow is unchanged.
Because it is a finance app, I would also use normal phone-security habits: a screen lock, current operating-system updates, and care when reviewing sensitive information in public. The Everyone age classification describes its store audience, not the seriousness of the financial choices a user may make inside it.
When I would choose something else
I would skip Ava if my primary need were a full financial command center. A bank app, budgeting platform, or credit-monitoring service could be more efficient depending on the task. I would also look elsewhere if I already had a credit card I managed well and wanted rewards, broad payment flexibility, or a more established card ecosystem.
I would be cautious if my income is irregular or my bills are already difficult to cover. In that situation, adding another financial obligation can increase stress. A conversation with a qualified financial counselor or a careful review of essential expenses may be more useful than installing another app.
I would also avoid choosing it solely because its rating is strong. The 1.7 thousand written reviews and large rating base indicate active user response, but popularity is not a substitute for reading the terms and matching the product to my circumstances. The right question is not whether other people like it; it is whether I can use it consistently and responsibly.
My recommendation after weighing the trade-offs
I recommend Ava Finance to beginners and rebuilders who want a focused, mobile-first way to approach credit-building and who are prepared to make consistency their main strategy. Its free entry point, approachable positioning, and dedicated purpose make it easier to consider than a crowded all-in-one finance app. I especially like it as a companion to a basic budget and bank alerts, not as a replacement for either.
My recommendation comes with a clear condition: use it deliberately. Set a review routine, understand the responsibilities attached to the product, and give the process realistic time. Do not install it expecting an instant score transformation or a complete picture of your finances.
For me, the decision is straightforward. If credit-building is the specific problem and I want guidance without starting with a complicated financial platform, Ava is worth trying. If I need broad money management, maximum card flexibility, or help with urgent debt and cash-flow problems, I would choose a different category first. Ava earns its place by staying focused, and that same focus is the reason it will not be ideal for everyone.
My final advice: treat Ava as a structured credit habit, not a financial shortcut. Used with a realistic budget and careful attention to obligations, it can be a sensible first step toward more confident credit management.
Pros
- Supports multiple digital assets for portfolio diversification.
- Provides automated yield strategies for hands-off earning.
- Offers transparent transaction records through blockchain data.
- Useful dashboard for monitoring balances and lending activity.
- Available on mobile devices for convenient account access.
Cons
- Crypto assets can lose value quickly due to market volatility.
- Yield rates may change and are not guaranteed over time.
- Some features may require familiarity with DeFi concepts.
- Network fees can increase the cost of certain transactions.
- Funds may face smart-contract and platform-related risks.
FAQs for Ava Finance
What is Ava Finance, and what can I use it for?
Ava Finance is a personal finance app designed to help users organize and monitor their money from a mobile device. Depending on the available features in your region, it may help you track spending, review financial activity, manage budgets, and understand your overall financial position. Before downloading, check the current app description because supported services and tools can vary by country and platform.
Is Ava Finance safe to use with my financial information?
Before connecting any accounts, review Ava Finance’s privacy policy, security information, and permissions carefully. Financial apps commonly use encryption, authentication, and secure connections, but no online service can guarantee absolute protection. Avoid sharing passwords through messages or unofficial websites, enable any available biometric or two-factor security options, and download the app only from the official Google Play Store or Apple App Store.
Does Ava Finance connect directly to my bank accounts or cards?
Ava Finance may offer account or card connectivity through supported financial institutions and third-party services, but availability depends on your country, bank, and the version of the app. During setup, the application should explain what information is requested and why. If your institution is not supported, you may need to enter transactions manually or use a different compatible account.
Is Ava Finance free, or does it include subscriptions and extra charges?
The download price and available features can differ between Android and iOS, and some functions may require a subscription, in-app purchase, or other fee. Carefully read the store listing and the pricing information shown inside the app before starting a trial. If a trial is offered, check its duration, renewal terms, cancellation process, and whether charges are handled through Google Play or Apple.
What should I check before downloading Ava Finance?
Before installing Ava Finance, confirm that your device meets the application’s operating-system requirements and that the app is available in your region. Review recent user feedback, the developer name, requested permissions, supported banks or services, and the date of the latest update. You should also decide whether the app’s privacy practices and features match your financial needs before creating an account.

Ava Finance
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via support@meetava.com, visit https://www.meetava.com, or review their https://www.meetava.com/legal/privacy.










